


House Price Growth Hits Almost 3-Year Low – What Does It Mean For You?
Leave it in the comments section at the bottom of this article.
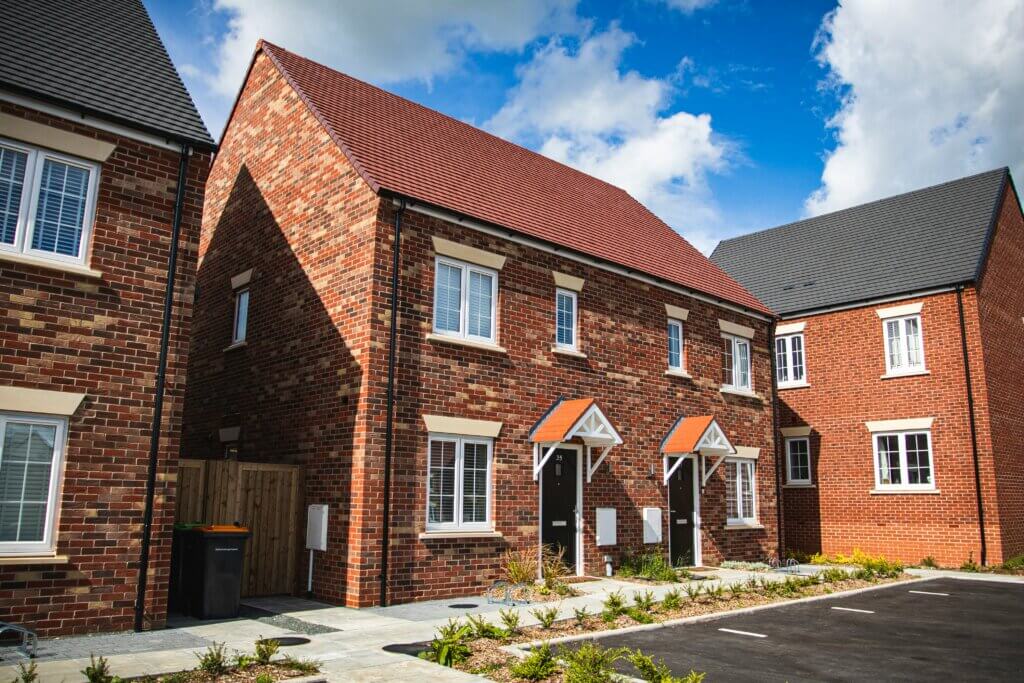
Annual UK house price growth in July, slowed to its lowest rate in almost 3 years, according to new data from Lloyds.
The current average house price is 0.1% higher than the same time last year, however, it’s the slowest rate of annual growth since November 2023
Average property prices remained effectively unchanged over the month at £299,253 compared to £299,396 in June.
It follows a slight rise of 0.2% from May to June this year.
Property growth in the South East struggles
Average house prices in the South East saw prices fall -2.0% year-on year to £381,146 in the year to July 2026.
Greater London also recorded a -1.3% decline in property price growth to £533,930.
By contrast, properties in the North of England recorded stable growth. The North East saw annual property growth of 2.8%, taking the average property price to £182,488 while the North West saw prices increase 2.1% to £247,836.
Property prices in Northern Ireland grew the most at 7.4% taking the average home cost to £231,131.
Scotland posted record growth with prices up 3.6% year-on-year to an average of £223,246.
Homes in Wales also saw annual growth of 1.6%, where the typical property now costs £231,458.
What does this mean for you?
Whether you’re a buyer or hoping to sell, taking time to improve your finances or property can help you achieve your financial aspirations.
For sellers, using slow periods in the market to boost the value of their homes could help ensure their properties are competitively priced.
For buyers, one of the most important factors is getting into the best financial position.
Taking time to review your finances, particularly your house deposit and credit score if you’re applying for a mortgage, can help boost your chances of getting a good deal.
You’ll also need to have money set aside for costs such as a house survey, legal fees and moving costs.
Some of the ways to maximise your savings is, by using a top-rate savings account or Cash ISA.
If you’re not looking to buy for at least another 5 years, investing using a Stocks and Shares ISA could help you build up a pot to help with homebuying costs.
Although bear in mind that your capital is at risk with investing. This means the value of your portfolio can go up or down and you might not get back everything you put into it.
Another product to consider is a Lifetime ISA, if you’re a first-time buyer, depending on the value of the home you’re looking to purchase.
For more tips, check out our podcast episode: The Truth About Buying a Home.
Comments
Related News

Savings tax bills soar by 76% for additional-rate taxpayers: Is HMRC taking more of your interest?
What kind of investor are you?












No comments yet. Be the first to share your thoughts!