


758,000 Young Savers Urged To Claim Free Cash
Leave it in the comments section at the bottom of this article.
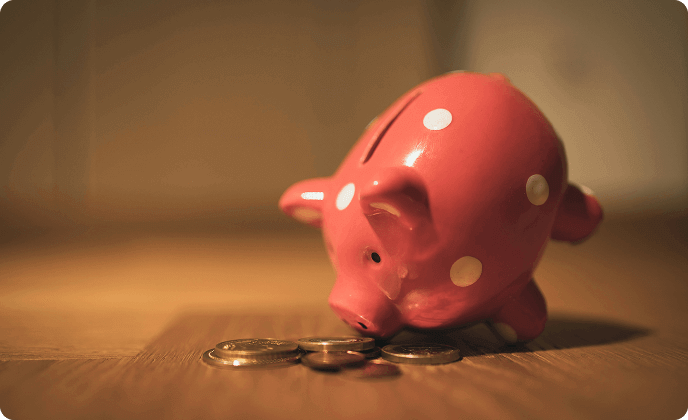

The government is urging 758,000 savers aged 18-23 years old to claim cash automatically opened for them at birth.
Child Trust Fund (CTF) accounts were set up by the government for children born between 1 September 2002 and 2 January 2011.
An initial deposit of at least £250 was added to each account. When the child turns 18, they can choose to withdraw the money or reinvest it.
The average unclaimed CTF is worth over £2,240.
You can claim a CTF by contacting the provider. If you’ve lost touch with a CTF account, you can recover your details using the Child Trust Fund finder.
You’ll just need to enter the account holder’s National Insurance number and date of birth.
The Child Trust Fund scheme ended in January 2011 and was replaced by Junior ISAs.
What can you do with a CTF?
There are several options available for your CTF once you turn 18. And the best option for you will depend on your financial circumstances.
For instance, if you’re heading into higher education, you might need to add your CTF cash into a student bank account to use for your expenses.
If you’re thinking about saving or investing your money, some of the options to consider include:
– Savings account: allows you to earn interest on your cash. Some accounts have restrictions on how often you can access your money. We’ve rounded up our pick of the best savings accounts to help you find the top rates.
– Cash ISA: is a type of savings account where you can earn tax-free interest. You can pay in up to £20,000 of your ISA allowance each tax year. It’s important to shop around and compare accounts to help you find the best Cash ISA for you.
– Lifetime ISA: is a savings account for people aged between 18 and 39 years old to save for their first home or retirement. You can put in up to £4,000 each tax year until you are 50. The government pays a 25% bonus (up to £1,000) on top of what you save. Lifetime ISAs come with restrictions on when you can access your money which are important to understand before signing up. If you think it’s the right account for you we’ve ranked our selection of the best Lifetime ISA providers.
– Stocks and Shares ISA: is an account that allows you to buy, sell and hold investments such as stocks and shares, bonds and funds. You can also hold cash, but not all Stocks and Shares ISAs pay interest on this! Our pick of the best stocks and shares ISAs can help you compare the top platforms on the market right now.
– Pension: is an account that allows you to save for retirement. You can add your CTF savings as a lump sum into a workplace pension,
personal pension or SIPP.
Comments
Related News

Savings tax bills soar by 76% for additional-rate taxpayers: Is HMRC taking more of your interest?
What kind of investor are you?












No comments yet. Be the first to share your thoughts!