


Average UK House Prices Slows – What Does It Mean For Buyers and Sellers?
Leave it in the comments section at the bottom of this article.
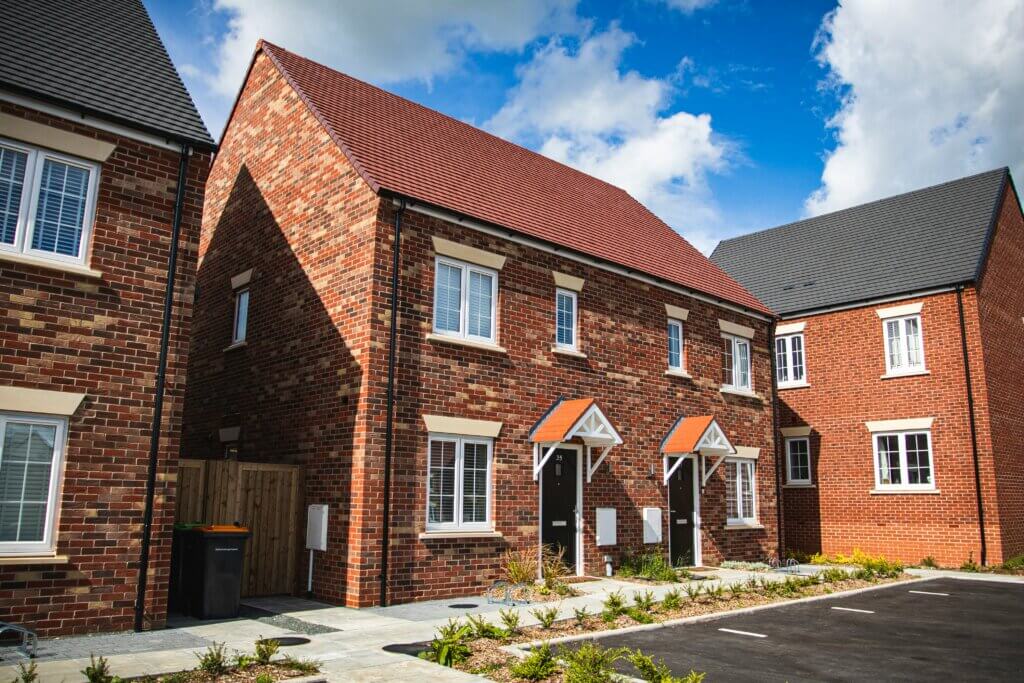
Annual UK house growth slowed to 1.7% in May compared to 3% in the previous month amid uncertainty caused by conflict in the Middle East, according to Nationwide.
The average property price stood at £278,024 in the 12 months to May 2026, down from
£278,880 in Apri, the latest Nationwide House Price Index revealedl.
However, prices are still higher compared to the same period last year when the average house price was £273,427.
The table below shows how much average property prices have changed:
| Headlines | May-26 | Apr-26 |
|---|---|---|
| Monthly Change* | -0.6% | 0.4% |
| Annual Change | 1.7% | 3.0% |
| Average Price (not seasonally adjusted) |
£272,998 | £272,226 |
* Seasonally adjusted figure (note that monthly % changes are revised when seasonal adjustment factors are re-estimated)
Uncertainty due to conflict in the Middle East, rising energy prices and interest rates are the largest drivers in house price growth slowing.
Robert Gardner, Nationwide’s Chief Economist said:
“UK annual house price growth slowed to 1.7% in May, from 3.0% in April. Prices fell by 0.6% month on month, after taking account of seasonal effects – the first monthly decline so far this year.
“Given the uncertainty caused by developments in the Middle East and the subsequent rise in energy prices and market interest rates, some loss of momentum was to be expected. Indeed, consumer confidence has weakened noticeably since the start of the conflict, with GfK’s headline index falling to its lowest level since late‑2023 in April, with only a marginal increase in May.”
What does this mean for buyers and sellers?
Although house price growth has slowed month on month, there has been a yearly rise of around £5,000, which is good news for sellers overall.
Taking time to boost the value of their homes could help ensure their properties are competitively priced.
For buyers, one of the most important factors is getting into the best financial position.
Taking time to review your finances, particularly your house deposit and credit score if you’re applying for a mortgage, can help boost your chances of getting a good deal.
It’s also vital to set enough money aside for additional costs such as a house survey, legal fees and moving costs.
One way to maximise your savings is by using a top-rate savings account or Cash ISA. If you have a longer time horizon, of at least 5 years, using a Stocks and Shares ISA could help you build up a pot to help with homebuying costs.
Another product to consider is a Lifetime ISA, if you’re a first-time buyer, depending on the value of the home you’re looking to purchase.
For more tips, check out our podcast episode: The Truth About Buying a Home.
Comments
Related News

Savings tax bills soar by 76% for additional-rate taxpayers: Is HMRC taking more of your interest?
What kind of investor are you?












No comments yet. Be the first to share your thoughts!